THE 2026 INSURANCE CRISIS
Insurance companies have changed the rules in 2026. They're now using drones, satellites, and AI to inspect properties remotely—and they're canceling policies or doubling premiums for seniors with deferred maintenance. This chapter shows you how to protect yourself.
Why Your Policy Is at Risk
Insurance companies are using three methods to identify high-risk properties:
- Drone Roof Inspections: Thermal imaging identifies moss, missing shingles, and structural sag invisible from the street
- Satellite Age Analysis: AI estimates roof age from aerial imagery—if it looks 20+ years old, expect non-renewal
- Claims History Mining: Even minor claims from 5+ years ago trigger algorithm flags for non-renewal
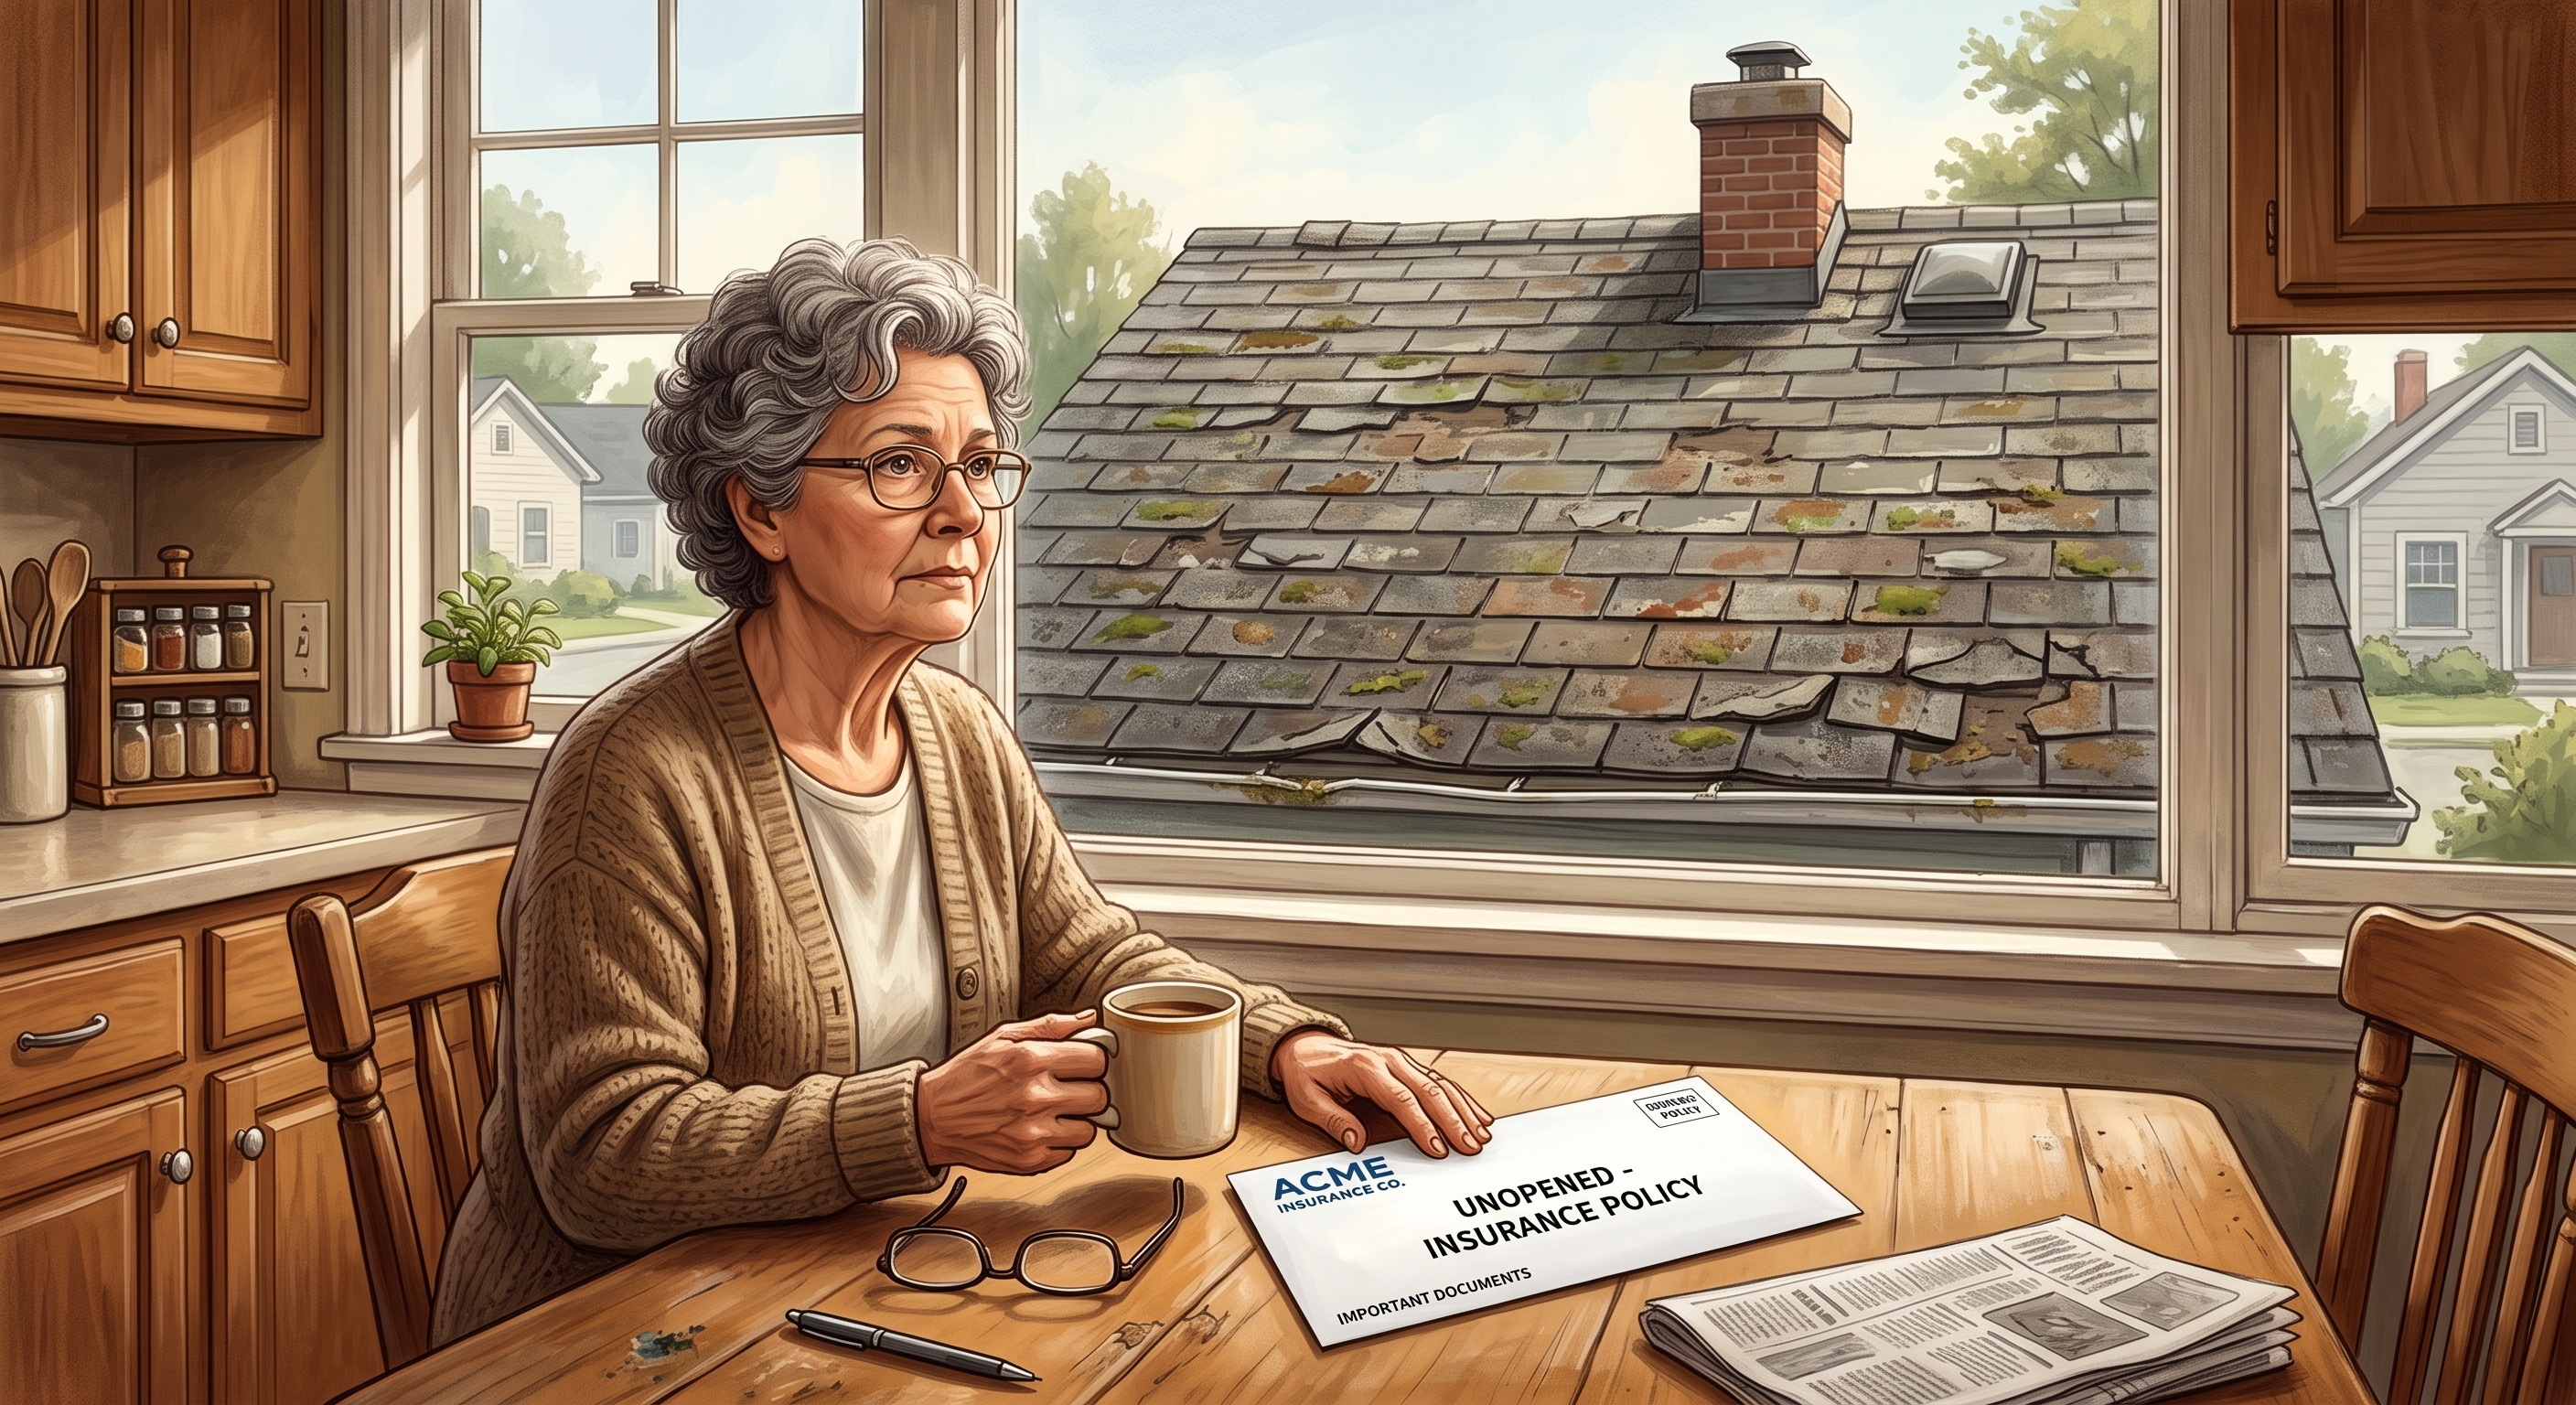
A CASE FOR MARTHA:
Martha, 74, received a non-renewal notice in January 2026. Her roof was 18 years old with minor moss. The insurer's drone inspection flagged it as 'high risk. ' She had 90 days to find new coverage. With a poor roof inspection, she couldn't get affordable insurance anywhere. She was forced to either: Replace the roof for $22,000, or Sell the house quickly before the policy lapsed. She chose option 2 and lost $30,000 in negotiating leverage because buyers knew she was desperate.
The 30 Day Insurance Audit
Complete this audit BEFORE your insurer does it for you
| Item to Inspect | 🚩Red Flag | Action |
| Roof Age | 15+ years old | Get professional inspection now; budget $15K-$25K for replacement or prepare to sell |
| HVAC Age | 20+ years old | Potential premium increase; not urgent but worth addressing |
| Electrical Panel | Fuse box or Federal Pacific panel | Fire risk, upgrade required or expect cancellation |
| Water Heater | 12+ years old | Replace preemptively: water damage claims are expensive |
| Claims History | 2+ claims in 5 years | Non-renewal likely; shop for new insurer now |
Decision Tree: Repair vs. Sell
Use this decision tree to determine whether to invest in repairs or sell now:
SCENARIO 1: Roof Needs Replacement ($20K-$25K)
- If staying 3+ years: Replace roof (ROI on sale price)
- If selling within 2 years: Sell as-is with price reduction
- If senior housing spot available NOW: Sell immediately, negotiate leaseback
SCENARIO 2: Multiple Deferred Maintenance Issues ($40K+)
- If insurance canceled in 90 days: Sell immediately
- If renewal premium doubled: Calculate monthly cost vs. selling timeline
- If home is too large to maintain: Sell and move to right-sized solution
SCENARIO 3: Insurance Still Affordable, Home Well-Maintained
- Document all maintenance with photos and receipts
- Preemptively share with insurer before drone inspection
- Continue with downsizing timeline (Chapters 2-7)
The Preemptive Documentation Strategy
- Don't wait for your insurer to inspect. Send them proof of maintenance BEFORE they flag your property:
- Hire a professional roofer for a written inspection report (cost: $200-$400)
- Take dated photos of all major systems: roof, HVAC, electrical panel, water heater, foundation
- Compile receipts for any repairs or replacements in past 10 years
- Send documentation packet to your insurance agent with cover letter stating: "Proactive maintenance verification for policy renewal"
- Request written confirmation that your policy is not at risk for non-renewal
What to Do If You Receive a Non-Renewal Notice
You typically have 30-90 days. Here's your action plan:
Week 1-2: Assessment Phase
- Get 3 quotes for identified repairs (roof, electrical, etc.)
- Shop for alternative insurance (expect 50-150% premium increase)
- Calculate monthly cost difference: Current premium vs. New premium vs. Selling costs
- Consult with real estate agent on current market value and realistic selling timeline
Week 3-4: Decision Point
If repair costs less than $15,000 AND you plan to stay 2+ years:
- Complete repairs immediately
- Document with photos and receipts
- Shop for new insurance with proof of repairs
If repair costs more than $25,000 OR selling timeline is less than 2 years:
- List house immediately (see Chapter 3)
- Disclose insurance issue to buyers upfront (prevents lastminute deal collapse)
- Price competitively—you're on a deadline
- Negotiate lease-back if needed (see Chapter 7)